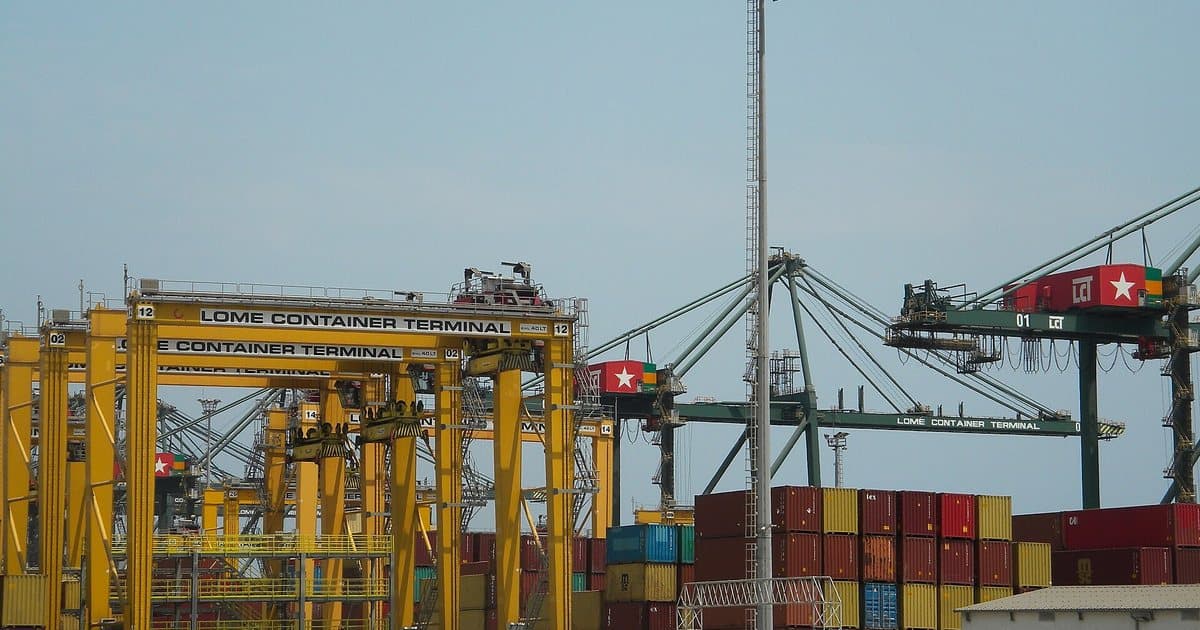
DDP and DAP look almost identical on paper. Under both, the seller carries the goods all the way to the buyer's door and bears the risk until they arrive. The difference is one word, duty, and in West Africa that word can be worth 40 percent of the value of the goods.
Here is what the two rules actually say, who pays what under each, what it costs in a real case in Senegal, and how to choose. One warning first: an offer reading "DDP, import duty for the buyer's account" is not DDP at all. It is DAP under another name.
Take action
- Ask for a delivered duty paid price on WhatsApp: goods, HS code, value, delivery address.
- Ship a container to Senegal: filings, duty and delivery, step by step.
- Source goods in Africa: vetted suppliers, inspection, delivery to your warehouse.
What the rules say
The Incoterms rules are published by the International Chamber of Commerce (ICC). The version in force is Incoterms 2020. As of 30 September 2026 no official text has replaced it, whatever the "Incoterms 2026" pages found online may suggest.
DAP, Delivered at Place. The seller delivers when the goods are placed at the buyer's disposal on the arriving means of transport, ready for unloading, at the named place. The seller clears the goods for export and transit. The buyer clears them for import and pays import duty and VAT.
DDP, Delivered Duty Paid. Same delivery point, same risk transfer. But the seller also clears the goods for import and pays all duties, VAT and taxes due on import. It is the rule that places the most obligations on the seller.
Under both rules, unloading at destination is the buyer's job unless the contract says otherwise.
Side by side
| DAP | DDP | |
|---|---|---|
| Transport to the named place | Seller | Seller |
| Risk until delivery at destination | Seller | Seller |
| Export and transit clearance | Seller | Seller |
| Import clearance | Buyer | Seller |
| Import duty, levies and VAT | Buyer | Seller |
| Unloading | Buyer | Buyer |
A worked example in Senegal
Take goods with a customs value of 10 million CFA francs (CIF: price, insurance and freight to the port), classified in category 3 of the ECOWAS common external tariff, which covers final consumer goods, arriving by sea in Dakar.
| Duty or tax | Rate | Amount |
|---|---|---|
| Customs duty (category 3) | 20% | 2,000,000 CFA francs |
| Statistical fee | 1% | 100,000 CFA francs |
| UEMOA community levy | 0.8% | 80,000 CFA francs |
| ECOWAS levy | 0.5% | 50,000 CFA francs |
| Senegalese Shippers' Council (sea only) | 0.4% | 40,000 CFA francs |
| VAT | 18% | 2,178,000 CFA francs |
| Total | 4,448,000 CFA francs |
VAT is not charged on the goods alone. Under article 368 of Senegal's General Tax Code, its base is the customs value plus the duties and taxes collected for the state budget, here the customs duty and the statistical fee: 12.1 million CFA francs, hence 2,178,000 CFA francs of VAT.
Under DDP, the seller advances about 4.45 million CFA francs to customs on goods worth 10 million, or 44.5 percent of their value. Under DAP, the buyer does. A category 4 product (35 percent duty) costs more; a category 1 industrial input (5 percent) much less. Hence the first rule for any DDP price: know the exact tariff classification before you quote.
The traps of DDP for a foreign seller
You must be able to import. The ICC itself warns that under DDP the seller may need to be registered as an importer and for VAT in the buyer's country. In Senegal, above 200,000 CFA francs of customs value, a declaration goes through a licensed customs broker unless you hold an authorisation to declare yourself, and the importer must be registered with the trade registry. A foreign company with no entity and no partner on the ground usually cannot do this.
You may lose the VAT. A Senegalese buyer registered for VAT can normally deduct the 2,178,000 CFA francs. A foreign seller that is not registered in Senegal cannot. That is why contracts often read "DDP, VAT excluded": it is common practice, provided it is written into the contract.
The destination country is not always the port country. DDP Bamako from Dakar means transit under customs control through Senegal, then Malian clearance and Malian taxes on arrival. The price must carry Mali's duties, not Senegal's. And since 2025 Mali, which left ECOWAS, applies the 0.5% levy of the confederation of Sahel states on goods from outside the confederation, presented by Bamako as replacing the former ECOWAS levy. A tax table copied from an old quotation is wrong.
Customs can revalue the goods. If the declared value is challenged, duty rises, and under DDP the seller pays the difference.
How to choose
Choose DAP when the seller cannot act as importer in the destination country, or when the buyer recovers VAT and prefers to pay it directly. It is the safer default for a foreign supplier without a local presence.
Choose DDP when the buyer wants an all-in price and never wants to deal with customs, and when the seller has a structure on the ground, its own or a partner's, that can import, classify the goods correctly and pay duties on time.
Our reading
DDP is the rule buyers prefer and sellers underestimate. For a foreign company that wants to sell into West Africa without setting up there, it is also the most powerful one: it takes customs out of the customer's life. But only if someone on the ground really knows how to import, classify, anticipate a revaluation and pay at the right moment. A DDP price quoted without a tariff line, a named importer and a margin for the unexpected is a wrong price.
Getting a DDP price right the first time: six facts
A DDP price is built on the tariff classification, not on the weight. To avoid three rounds of questions, send from the start:
- An exact description of the goods, and the HS code if you know it.
- Their value, with the invoice or pro forma.
- Their origin, with the certificate of origin if there is one: it can change the duty.
- The port of loading and the supplier's Incoterm, to rebuild the CIF value.
- The exact delivery address: Dakar, Touba or Bamako is not the same road, nor the same customs.
- Unloading means on site: dock, forklift, crane, or none.
With these six facts, the classification is checked before the price, and the price does not move on arrival.
Frequently asked questions
What is the difference between DDP and DAP?
Under both rules the seller delivers at destination and bears the risk until then. Under DDP the seller clears the goods for import and pays duty and VAT; under DAP the buyer does.
Who pays import duty under DDP Incoterms?
The seller, together with import VAT and other import taxes, unless the contract expressly excludes them, for instance "DDP, VAT excluded".
Does DDP transfer ownership of the goods?
No. Incoterms rules allocate costs, risks and formalities; they do not deal with transfer of title, which depends on the sales contract and the applicable law.
Can a foreign company sell DDP into Senegal without a local entity?
Rarely. Above 200,000 CFA francs of customs value, the declaration goes through a licensed customs broker, and the importer must be registered with the trade registry. A foreign seller works through a local company, its own or a partner's.
Does DDP include unloading?
No. Delivery takes place with the goods ready for unloading; unloading is the buyer's job unless the contract says otherwise.
Is there an Incoterms 2026 version?
No. The rules in force are Incoterms 2020. As of 30 September 2026, the ICC has published no replacement.
What we do
GraceRoad delivers duty paid into West Africa: we organise transport, transit and customs clearance through licensed brokers, and hand over the goods on your site at a price that includes the destination country's duties and taxes. For a foreign seller, we can also act as the local relay for import. Send us the nature of the goods, their value and the delivery point: we check the tariff classification first.
Take action
- Ask for a DDP price on WhatsApp: we check the tariff classification first.
- Email your pro forma invoice to contact@graceroad-group.com: we tell you what customs will cost before you quote your buyer.
- Arrange trucking in West Africa: vetted hauliers across the region.
Read next: quoting DDP into West Africa and customs valuation disputes in West Africa.
Sources: International Chamber of Commerce, Incoterms 2020 rules, DAP and DDP rules and explanatory notes, as summarised by Trade Finance Global; French customs (DGDDI), "10 questions pour exporter au Sénégal", 21 February 2020 (common external tariff categories, UEMOA and ECOWAS levies, statistical fee, VAT, Senegalese Shippers' Council, 200,000 CFA franc threshold and licensed customs broker); AD'OCC, Senegal country sheet (registration and importer card); Senegal General Tax Code, law 2012-31, article 368 (import VAT base); Le Soleil, 30 March 2025 (0.5% levy of the confederation of Sahel states).